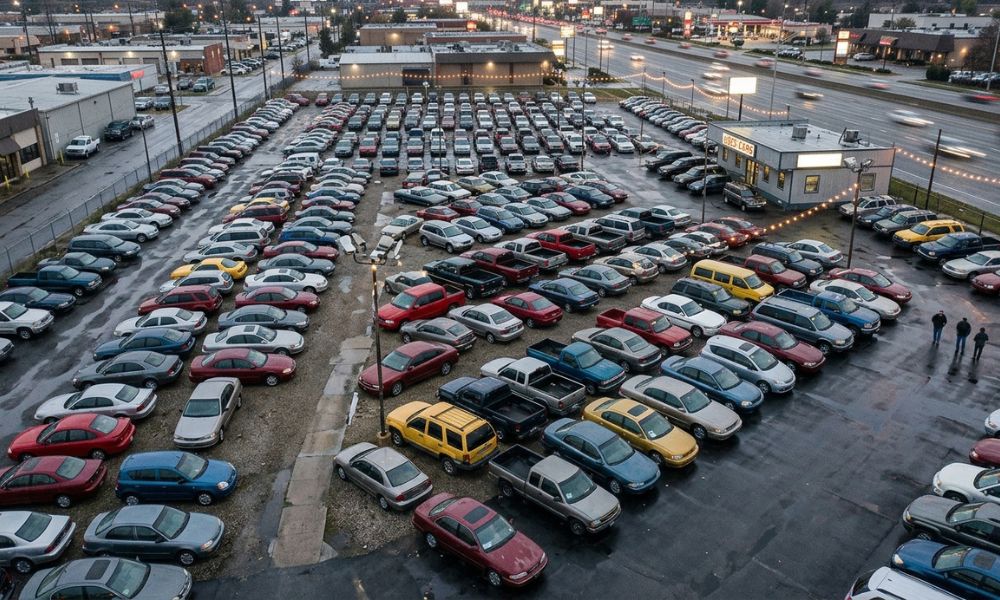
The Securities and Exchange Commission has accused three former executives of Texas subprime auto lender Tricolor of defrauding investors in asset-backed securities, alleging they concealed an approximately $800 million shortfall in collateral. The complaint, filed August 19, 2026, in the U.S. District Court for the Southern District of New York, names the company's founder and CEO, its CFO, and a senior finance director. Tricolor, which sold used cars and originated subprime loans, filed for Chapter 7 bankruptcy in September 2025.
According to the SEC, Tricolor raised more than $1.9 billion by selling bonds backed by pools of auto loans to institutional investors, with three broker-dealers acting as underwriters. The regulator alleges that the executives engaged in “double-pledging,” assigning the same loan to multiple bond deals or credit facilities simultaneously. The complaint also claims the collateral pools included “dead loans”—loans on which borrowers had stopped paying—and fictitious loans created with fabricated vehicle identification numbers.
The alleged scheme relied on falsified monthly reports that lenders and investors used to monitor the collateral. The SEC quotes a text message from the CFO describing a batch of collateral as “garbage, zombie loans which were ineligible anywhere.” The filing further alleges that the executives operated an off-the-books entity, referred to as “Company 23,” to hold dead loans and make them appear current.
A forensic firm hired by the bankruptcy trustee concluded that Tricolor had overstated its collateral by at least $675 million, according to the SEC. The regulator says the total missing collateral reached roughly $800 million. When lenders began questioning anomalies in mid-2025, the complaint alleges the CEO proposed cover stories, including a “system issue,” and agreed to delete an encrypted messaging chat he had suggested naming “911.”
Tricolor placed more than 1,000 workers on unpaid leave just before filing for Chapter 7 bankruptcy on September 10, 2025. The SEC alleges that during this period, the CEO drew a salary that reached $2 million in 2025, received a $15 million “special” bonus, and purchased a Miami home for approximately $18 million. The regulator is seeking to claw back those funds, impose penalties, and bar the CEO and CFO from serving as officers or directors of any public company.
The case underscores the reliance of asset-backed securities investors on the accuracy of collateral data. One repeat buyer told the SEC that any double-pledging was a “bright line” it would never have crossed, highlighting the trust that underwriters and institutional investors place in such disclosures. The SEC's action follows other recent enforcement efforts, including allegations against Adit Ventures over a misrepresented stake and fund misuse, and a lawsuit against modular builder S2A for misusing investor funds.
For financial advisors and institutional investors, the case serves as a reminder of the importance of due diligence in structured credit. While the SEC's complaint is not a finding of liability, it illustrates how far collateral quality can drift from reality before detection. The industry may also watch for potential changes in underwriting standards and disclosure requirements, particularly as regulators have recently proposed raising insider lending thresholds, signaling a broader focus on lending practices.


