The Securities and Exchange Commission's recent proposals to broaden retail participation in private markets could be misread as a loosening of oversight. But compliance consultants caution that alternative asset managers entering regulated fund structures will encounter significantly more demanding requirements around valuation, liquidity, and board governance.
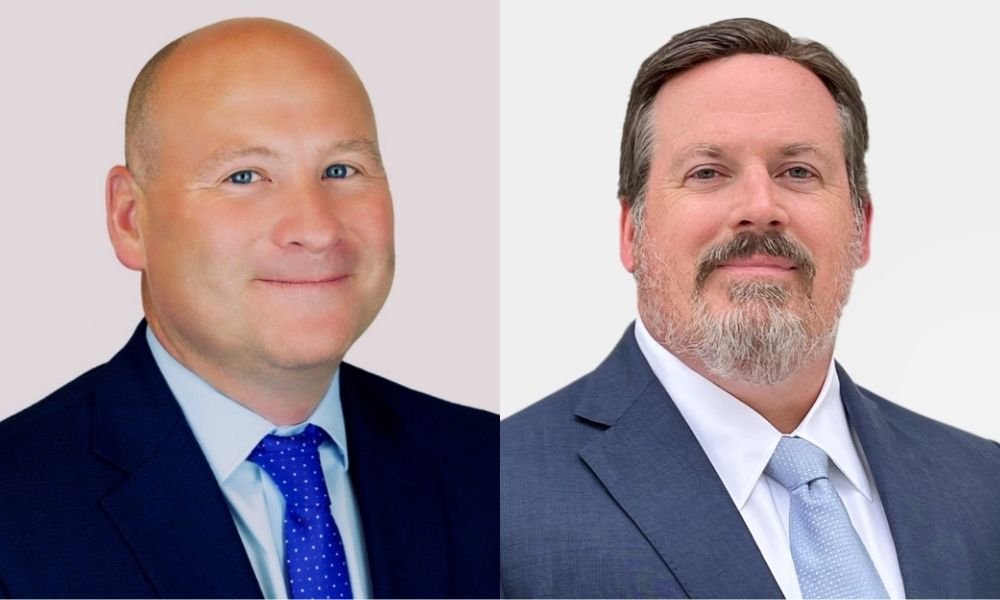
"Private-market retailization may look like deregulation from the outside, but for many managers it will mean stepping into a much more complex compliance environment," said Dan Campbell, managing director at ACA Group, a New York-based compliance advisory firm. He added that managers accustomed to institutional and high-net-worth clients could face a "culture shock" as they adapt to independent governance, rigorous valuation methodologies, and enhanced investor disclosures.
Shane McGreevy, a compliance consultant at STP Investment Services in West Chester, Pennsylvania, framed the SEC's approach as an attempt to expand access without dismantling investor protections. "That's really the balance the SEC needs to strike: how do you give more investors access without losing the protections that are there for a reason?" he said, pointing to the SEC's proposals on interval funds and performance-based compensation as evidence of that balancing act.
What the SEC has proposed
The commission voted in March to allow advisors to regulated funds to charge performance-based fees capped at 20% of net gains, provided a board with a majority of independent directors approves the arrangement. It also proposed letting interval funds offer monthly repurchases and replacing the fixed liquidity requirement with a principles-based approach. Separately, the SEC is considering whether holders of CFP, CFA, and CPA credentials should qualify as accredited investors, a move that would expand the pool of eligible investors for private offerings. These changes follow an executive order that opened 401(k) plans to private equity and other alternative assets.
Valuation and liquidity challenges
Campbell stressed that retail distribution does not make valuing alternative assets any easier. "The underlying assets don't become easier to value simply because they're being offered to a broader investor base," he said. "As private markets move further into regulated and retail structures, firms will need much stronger governance around valuation methodologies, consistency across vehicles, and independent challenge of difficult marks." McGreevy echoed that sentiment, noting the SEC's recent scrutiny of private credit valuations as a reminder that managers must ensure their marks reflect underlying cash flows and economic reality.
Interval funds have become a primary vehicle for advisors to access private credit. Campbell warned that looser redemption terms heighten the importance of liquidity oversight. "Greater flexibility around redemption terms makes liquidity governance more important, not less," he said. "When you pair periodic investor liquidity with inherently illiquid private assets, firms need to be able to demonstrate how they define available liquidity, stress-test it, and communicate redemption expectations consistently."
For advisors, McGreevy emphasized that client education is as critical as access. "The key is making sure investors understand what they're getting into," he said. "Private markets are very different from public markets, particularly when it comes to liquidity, valuation, and risk. You may not be able to sell an investment when you want to, and determining what it's worth isn't always as straightforward as looking at a market price."
As the SEC's proposals move toward adoption, alternative managers will need to invest in compliance infrastructure to meet the heightened expectations. The industry is already seeing operational hurdles as private market access expands, and firms that fail to adapt may find themselves at a competitive disadvantage. The shift toward retailization is not just a regulatory change; it is a fundamental transformation of how private market investments are governed and disclosed.


