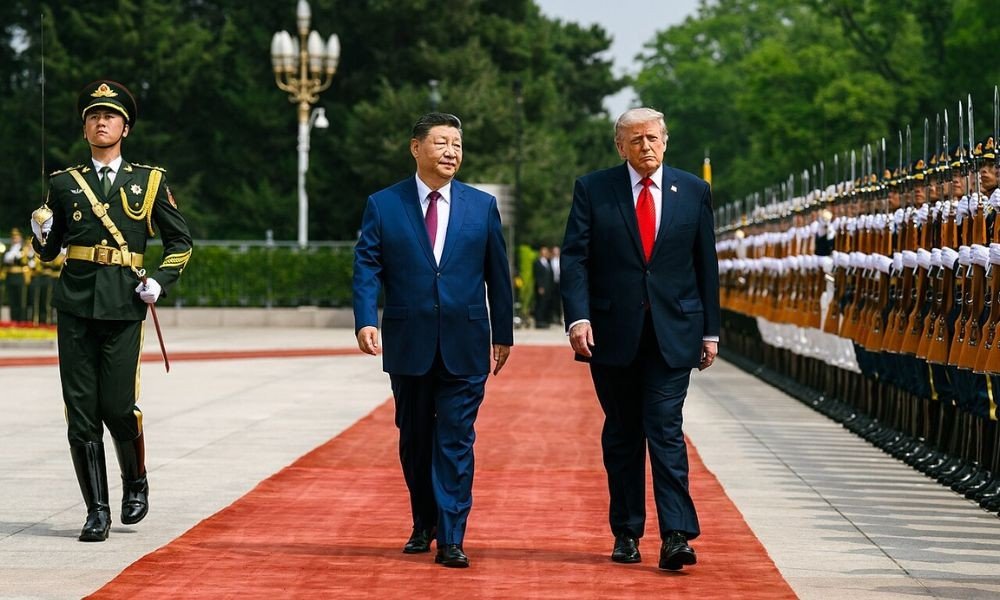
President Donald Trump is scheduled to host Chinese President Xi Jinping at the White House on Thursday for a summit that could influence trade policy and market sentiment. The meeting follows a February gathering in Beijing that was intended to reset relations after years of tariffs and tech restrictions. However, unresolved disputes over artificial intelligence and critical minerals remain.
On Sunday, Treasury Secretary Scott Bessent met with Chinese Vice President He Lifeng at JPMorgan Chase's Manhattan headquarters, alongside U.S. Trade Representative Jamison Greer. Bessent described the talks as "very successful," noting that the two sides discussed establishing a U.S.-China AI dialogue and a notification mechanism for AI-related incidents that reach "a national security level." He emphasized the importance of transparency between the world's two leading AI powers.
Markets responded positively on Monday, with AI-related equities outperforming. Palantir Technologies (PLTR) rose 2.4%, Alphabet (GOOG) gained 2.1%, and Arista Networks (ANET) climbed 2.5%, while the S&P 500 advanced 1.4% and the Nasdaq composite added 2.1%. Nvidia (NVDA), a key AI chipmaker, was up 2.2%. The gains suggest investors are optimistic about a constructive outcome, but advisors should note that such sentiment can reverse quickly.
The summit's agenda also includes critical minerals. According to Chinese customs data cited by the Financial Times, shipments of rare earth magnets from China to the U.S. fell last month. These magnets are essential for U.S. manufacturing in technology and defense sectors. The decline could signal that China is using export controls as leverage, a point of tension likely to surface during the talks.
Market analysts are watching for signals. Fadi Al Kurdi, CEO of FFA Kings, said in a note that a constructive outcome could support risk appetite. ING FX strategist Franco Pesole noted that positive trade headlines might provide some support to the dollar, though he cautioned that the summit is unlikely to be a major market event on its own.
For advisors, the key is not the summit's immediate headlines but the follow-through. A softer tone on AI and trade could extend the rally in names like Palantir, Alphabet, and Nvidia. However, portfolios with concentrated AI exposure carry elevated event risk heading into Thursday. Advisors should prepare clients for potential volatility in either direction.
China-focused AI investments are also in play. Last week, EMQQ Global launched the China AI ETF (ticker: AICH), which offers exposure to Chinese AI companies. Advisors with clients in such funds should be ready to explain how shifts in U.S.-China relations could affect those holdings.
Beyond AI, critical minerals are a growing friction point. Advisors overseeing exposure to U.S. manufacturing and industrials should watch for supply-chain disruptions. A breakdown in talks could lead to further export restrictions, affecting companies that rely on rare earth imports.
Related developments in Washington include the ESOP valuation bill and Treasury's proposed rules for Trump Accounts, which may also influence client portfolios. However, the immediate focus remains on Thursday's summit and its implications for trade and technology policy.