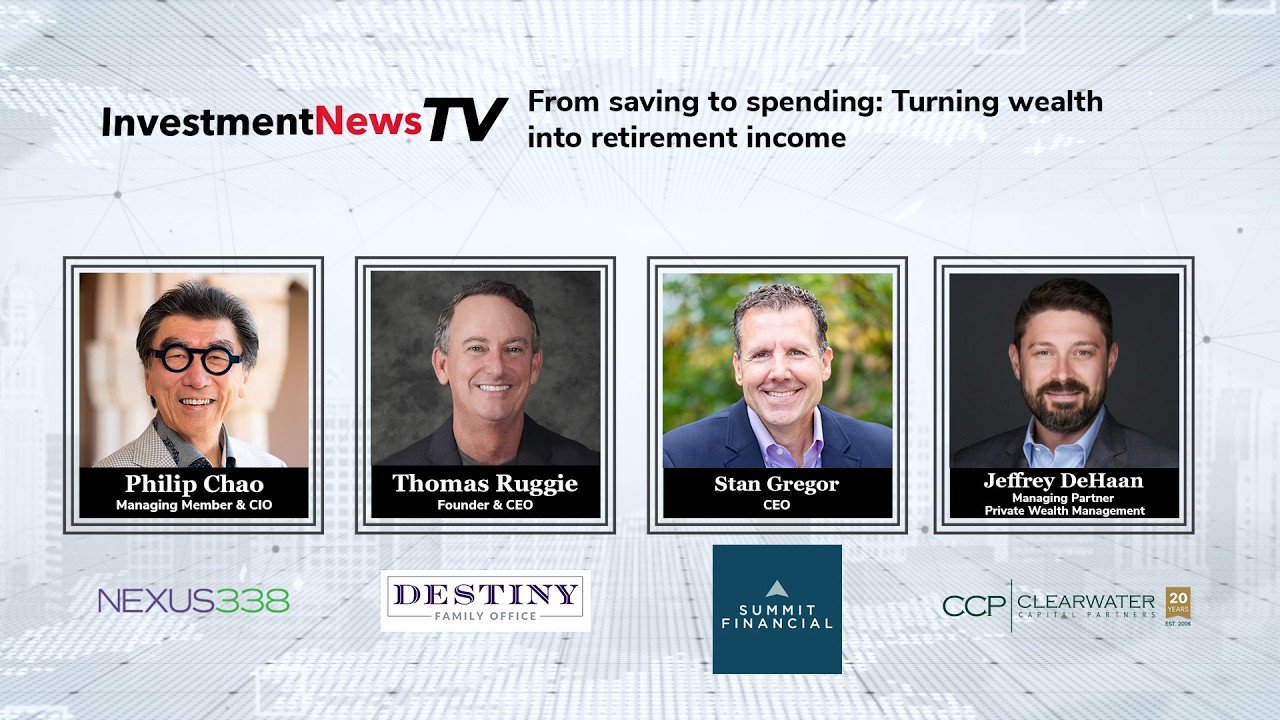
Retirees who have spent decades accumulating wealth often find the shift to spending it psychologically and financially challenging. In a recent InvestmentNews TV panel, four advisors—Jeffrey DeHaan, Stan Gregor, Philip Chao, and Thomas Ruggie—discussed how financial professionals can help clients navigate this transition, focusing on longevity risk, withdrawal strategies, and the rising cost of healthcare.
Longevity risk—the possibility of outliving one's assets—remains a central concern. The panelists noted that with life expectancies increasing, retirees need to plan for income streams that may last 30 years or more. According to a recent HSBC report, affluent U.S. investors face a $1.25 million retirement savings shortfall, underscoring the magnitude of the challenge.
Healthcare costs are a significant driver of that shortfall. The panel highlighted that a 65-year-old couple retiring today may need approximately $185,500 for medical expenses in retirement, a figure that continues to rise. Advisors are increasingly turning to Health Savings Accounts (HSAs) as a tax-advantaged tool to cover these costs, as noted in a recent analysis of HSA strategies.
Withdrawal rates were another key topic. The classic 4% rule, while still a starting point, may need adjustment given current market conditions and low bond yields. Chao suggested that a dynamic withdrawal approach—one that adjusts spending based on portfolio performance and inflation—can be more effective than a fixed percentage. He emphasized the importance of flexibility, especially in the early years of retirement when sequence-of-returns risk is highest.
The panel also addressed the psychological shift required to move from accumulation to decumulation. Many retirees, particularly those who have been disciplined savers, struggle with the idea of spending principal. Gregor noted that advisors can help by reframing retirement income as a paycheck replacement, using systematic withdrawals or annuities to create a steady cash flow. This mindset shift, he argued, is as important as the financial mechanics.
Inflation remains a wildcard. The panel cited a Transamerica survey showing that 78% of workers say inflation hampers their retirement saving, and retirees face similar pressures. Advisors must build inflation protection into income plans, whether through Social Security timing, Treasury Inflation-Protected Securities, or equities with pricing power.
Social Security claiming decisions were also discussed. Delaying benefits until age 70 can increase monthly payments by 8% per year, a guaranteed return that is hard to beat. However, the panel acknowledged that not all clients can afford to wait, especially if they face health issues or job loss. The recent TIAA survey found that 43% of workers have cut retirement savings amid concerns about Social Security's future, highlighting the anxiety around this decision.
Finally, the advisors emphasized the importance of a comprehensive plan that integrates tax planning, estate planning, and charitable giving. With taxable accounts now totaling $66 trillion, according to a recent H&W wealth report, advisors must consider the tax implications of withdrawals from different account types. By sequencing distributions strategically—drawing from taxable accounts first, then tax-deferred, and finally tax-free—clients can minimize their lifetime tax burden.
In conclusion, the panel agreed that successful retirement income planning is not just about numbers but about giving clients confidence. By addressing longevity risk, healthcare costs, and the psychological barriers to spending, advisors can help retirees enjoy the wealth they have built. As Ruggie put it, "Our job is to make sure clients don't run out of money, but also don't miss out on living."