As artificial intelligence tools become more embedded in personal finance, wealth advisors face a pressing question: will AI replace them? Two experienced practitioners argue that the answer hinges on the advisor's role—transactional or transformational.
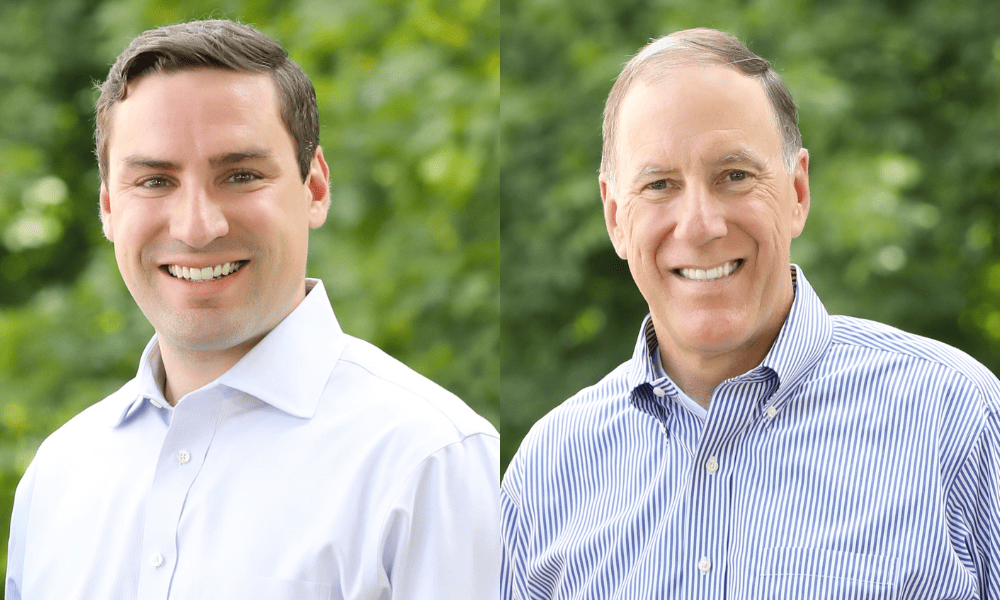
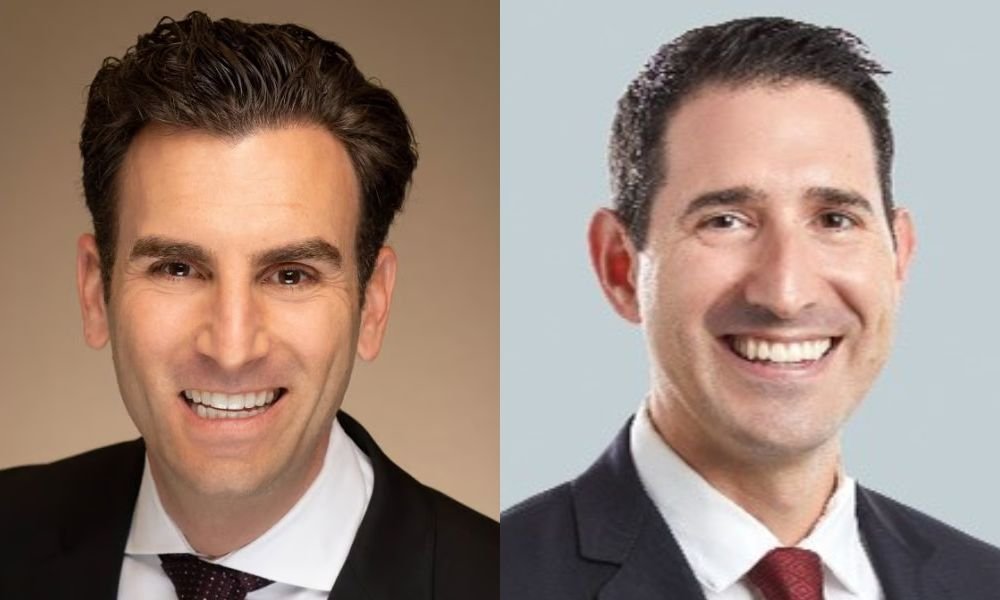
Adam Spiegelman, a wealth advisor at Spiegelman Wealth Management, and Joshua Landsman, a senior wealth strategist at Wilmington Trust, shared their insights with InvestmentNews. Their conclusion: AI is a powerful informational tool, but the core of financial coaching and strategic planning remains irreplaceably human.
Spiegelman draws a clear distinction between what AI can and cannot do. "AI is really, really good at the informational layer," he said. "It's weak at the transformational layer." He notes that AI can quickly calculate required minimum distributions, model Roth conversions, evaluate tax returns for harvesting opportunities, or flag budget inefficiencies. However, it cannot comfort a frightened client during market downturns or craft a college funding strategy for an unexpected acceptance. "AI can tell you kind of what to do," Spiegelman added, "but it doesn't sit with you when you're scared because the market is crashing."
Landsman, who spent a decade in private estate planning law before joining Wilmington Trust, sees AI as a validation tool. Clients increasingly arrive at meetings after running their financial questions through AI prompts, seeking a second opinion from a human who understands their full picture. "AI provides good concept summaries, but clients aren't 'issue spotters,'" Landsman said. "They may not reveal critical details like family members with special needs, net worth figures, or how assets are titled."
Neither advisor dismisses AI's utility. Spiegelman, a second-generation advisor who broke away from Commonwealth to launch his own RIA, has used AI software like conversation intelligence platform Zocks for months. "I walk into every single meeting better prepared than I ever could have been, literally because of AI," he said. Zocks flags when he speaks too much, surfaces conversational nuances, and detects behavioral signals—such as a client logging into their account 23 times during volatile trading. "Maybe that warrants a call," Spiegelman noted. "If meetings were basketball games, the AI would get credit for making a huge assist."
Jump's 2026 Financial Advisor Insights Report, analyzing thousands of anonymized advisor-client meetings, found that advisors with high Emotional Intelligence Scores lifted clients' spirits by an average of 17.5% during meetings. Landsman points to AI's role in organizing raw financial data—budgets, cash flow summaries, and balance sheets—that clients rarely have ready. "AI can serve as a productivity tool by interpreting personal financial data," he said. "Having AI organize client data in a useful format is a time-saving technique that makes it easier for advisors to evaluate situations."
Spiegelman is blunt about who should worry: "Transactional advisors are at risk." Those who focus on trade execution, fund selection, or basic data retrieval face obsolescence as AI performs these tasks faster and cheaper. Advisors who build genuine coaching relationships, however, will thrive. "Advisors won't be replaced by AI," he said. "They'll be replaced by advisors who use AI better."
Landsman echoes this from the high-net-worth perspective. While wealthy clients use AI as a fact-checking tool, he sees no risk of trusted advisors being fired. "Advisors who truly provide advice and interpret data rather than just receive it won't be outpaced by AI," he said. "Those at risk are professionals with 'advisor' titles who don't actually provide advisory value."
For advisors seeking to sharpen their edge, the message is clear: leverage AI for data and efficiency, but double down on the human skills of empathy, strategic thinking, and personalized coaching. As the industry evolves, the gap between good and great advisors will only widen.