After a prolonged period where a handful of mega-cap growth stocks—the so-called Magnificent Seven—drove the bulk of market returns, the investment landscape is showing signs of broadening in 2026. This shift is prompting financial advisors to increasingly incorporate dividend growth strategies into client portfolios, not merely as an income tool but as a means to diversify return sources and mitigate concentration risk.
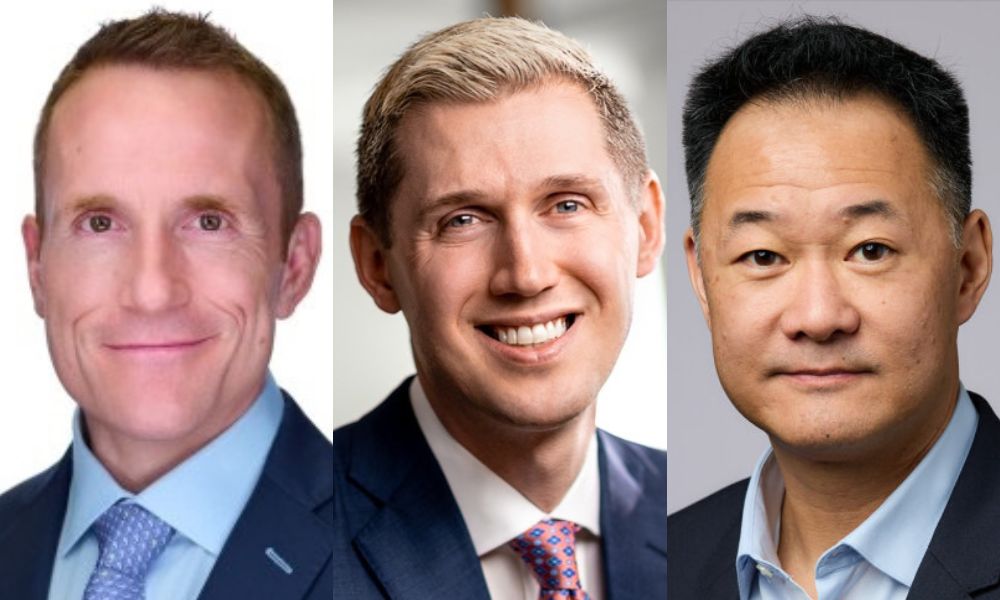
Justin Samples, a private wealth advisor at Ameriprise Financial, emphasizes that dividend investing is often misunderstood as purely an income play. In reality, it serves as a portfolio construction tool. With returns historically concentrated in a small group of large-cap growth companies, many portfolios have inadvertently built up significant concentration risk. Dividend-growing companies—typically those with durable cash flows, disciplined capital allocation, and mature business models—offer diversification benefits and a behavioral edge: a steadily increasing income stream can help clients remain invested during market volatility.
"Ultimately, the best portfolio is not simply the one that looks optimal on a spreadsheet; it is one that supports the client's financial plan and that they can stick with through a full market cycle," Samples said. "Given the extended period of growth-stock leadership, we think dividend growth can be a valuable complement to growth-oriented equities—not as a tactical bet against technology or innovation, but as a way to diversify the sources of return."
Nick Puncer, portfolio manager at Bahl & Gaynor, frames the case in terms of return-stream diversification rather than timing market leadership shifts. He argues that diversification is less about owning more securities and more about owning businesses whose fundamental drivers differ from what a client already holds—particularly if that portfolio is heavily weighted in mega-cap tech. "We believe a worthy goal is to broaden the ways in which the portfolio can succeed rather than making tactical calls on when market leadership will change," Puncer said. "Dividend growth can help through return source and underlying business diversification."
Quality over headline yield
All three experts agree that headline yield is a poor screening tool. Samples prefers a great company yielding 2% or 3% that consistently grows earnings and dividends over a struggling company yielding 7% or 8%, since an unusually high yield can signal the market doubts the payout's sustainability. His team weighs free cash flow, balance-sheet strength, payout ratio, earnings growth, and management's capital-allocation record over the size of the yield itself.
Puncer adds that headline yield reveals little about business durability, as it can simply reflect a falling stock price or an unsustainable payout. "Our focus is on companies we believe can support a growing dividend over time through cash flow generation, balance sheet strength, and other fundamental characteristics that signal quality," he said. "A growing dividend is not only valuable as an income source but also a tangible signal of management's ability to deploy capital and their confidence in future growth."
Christian Chan, chief investment officer at AssetMark, describes the current environment as broadly mid-cycle, with strong capital spending alongside late-cycle pressures such as elevated inflation and rising rates—a backdrop that favors quality dividend growers over the highest yielders. Chan also points advisors toward Europe, which offers higher yields, lower valuations, and heavier weighting in financials, industrials, and healthcare compared to a U.S. market dominated by technology stocks. "At this stage of the cycle, I would favor companies that can grow their dividends, not simply those offering the highest yield," Chan said. For taxable investors, he adds, after-tax yield matters more than headline yield, since "a dividend is only as durable as the cash flow behind it, and the yield that matters most is what the investor keeps after taxes."
Bridging fixed income and equities in retirement
For clients approaching or in retirement, all three advisors describe dividend growth as a complement to fixed income rather than a replacement. This pairing has drawn renewed attention as fixed income investors weigh quality against yield and risk heading into 2026. Samples says the goal isn't building a portfolio that generates enough dividends and interest to cover every dollar a client spends—that can push people to chase yield. Instead, he starts with the financial plan and layers multiple income sources: Social Security, pensions, interest, dividends, and strategic withdrawals. "For someone who may spend 25 or 30 years in retirement, that growth is critical," he said.
Puncer notes that fixed income provides contractual income and stability while dividend-growing equities offer participation in long-term business growth. He calls dividends "a tangible element of portfolio return that can replicate the familiarity of a regular paycheck for some clients." Chan agrees that dividend growth should complement, not replace, fixed income, allowing retirees to diversify income across bonds, credit, real assets, infrastructure, and equities while coordinating a tax-managed withdrawal strategy. This approach echoes broader retirement income planning coverage, which increasingly emphasizes coordinating guaranteed and market-based income sources rather than relying on any single bucket.
Recent data underscores the trend: U.S. dividend growth hit 8.7% in Q2, led by technology and financials, according to a recent report. Meanwhile, equal-weight S&P 500 ETFs have surpassed $100 billion in assets as advisors rethink concentration. These developments, along with rising private market allocations and concerns about AI-driven concentration, are prompting a broader conversation about portfolio construction. As Chan puts it, the key is to diversify not just across asset classes but across the fundamental drivers of return.



