The wave of mega-RIA formation through rapid mergers and acquisitions has prompted speculation about whether these large, privately held platforms can successfully pursue initial public offerings. The Echelon Partners 2025 RIA M&A Deal Report suggests that the reopening of public markets has made IPOs a viable option for scaled, profitable firms, potentially validating valuation expectations across private markets.
According to the report's authors, an increasing number of institutional-quality RIAs now exceed $10 billion in enterprise value, creating a credible pipeline of firms with the scale, durability, and operating maturity to consider public listings. For advisory firms with diversified, fee-based revenue, durable margins, and strong governance, public markets offer a path to liquidity and growth.
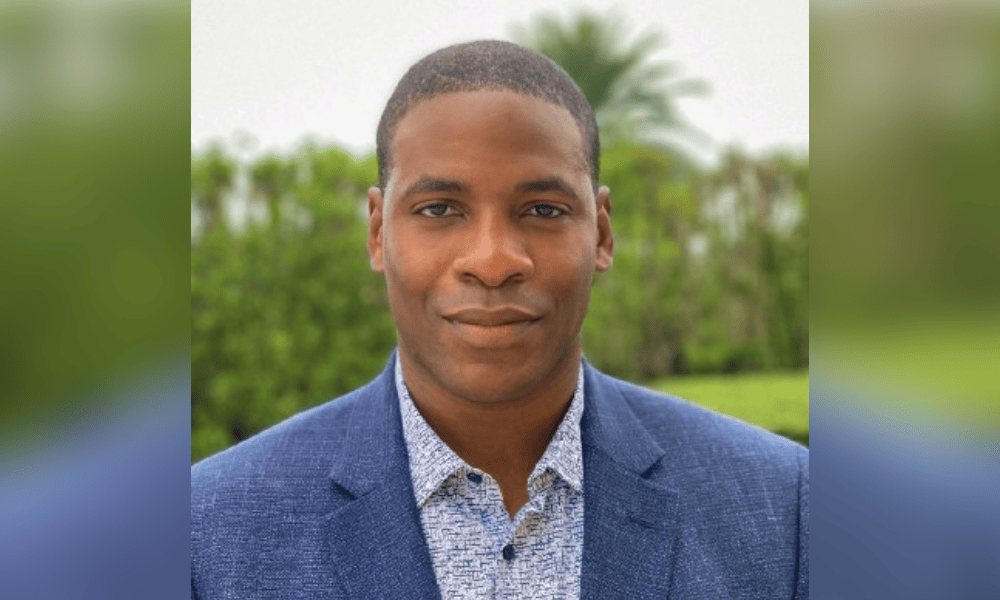
However, two veteran RIA founders caution that the critical factor for IPO readiness is not merely scale but the degree of integration. Ryan Halliday, founder of Crewe Advisors, asserts that firms racing toward $100 billion-plus in assets under management through acquisition must ask whether they are building for long-term growth. “I think the firms that are aggregating but integrating have a real opportunity to continue to grow and scale,” Halliday said. “It will be interesting to see if those that are just aggregating but aren’t integrating the firm can sustain that growth.”
Halliday emphasizes that going public is not structurally harder for mega RIAs aspiring to be the next LPL or Raymond James. The real test lies in checking boxes such as organizational integration, cultural fit, and a deep leadership bench. “The question is, are they building out their infrastructure and leadership infrastructure to handle geographic spread, different types of firms, and lift-outs of advisor teams from wirehouses?” he said. “It’s a challenge to have a consistent client experience at a firm that is aggregating rapidly without intentional integration and leadership across their platform.”
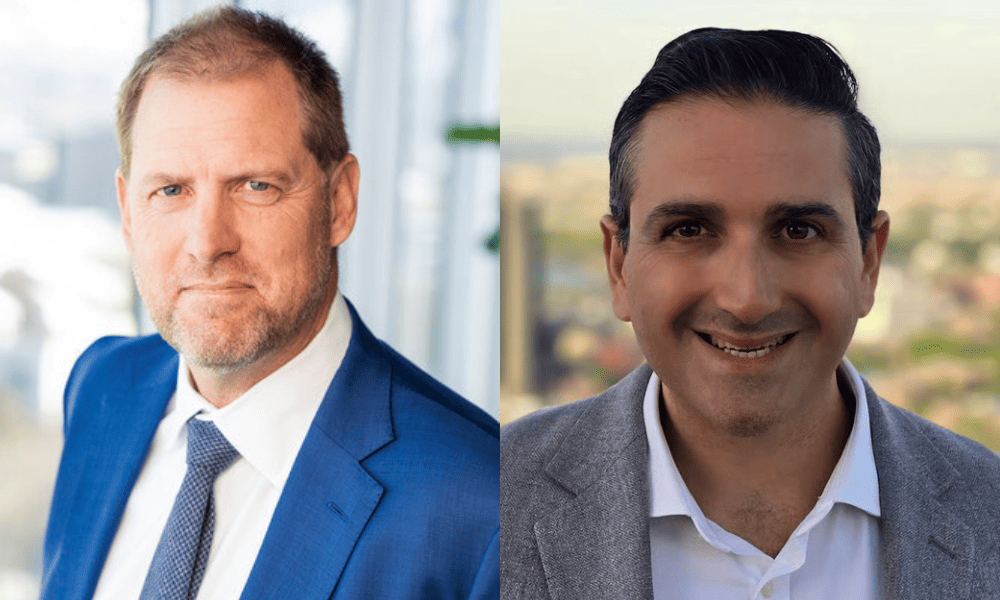
Eric Amar, founder and CEO of Accelerated Wealth Partners, spent a decade as chief growth officer at Focus Financial Partners, which went public in 2018 and was taken private by Clayton, Dubilier & Rice in 2023. Amar notes that on paper, RIAs should make excellent public companies due to recurring revenue, low capital intensity, high margins, and strong organic growth. However, he points out that the problem investors had with Focus was not the underlying business but the complexity of its decentralized, multi-affiliate model. “That structure was harder for investors to underwrite than a single, unified business,” Amar said. “Some of the disclosure around how the model worked could have been clearer, making it more difficult for the stock to be understood and valued on its merits.”
Amar argues that a collection of affiliates not woven into a single, legible story is a harder sell to public investors than a truly integrated platform. This gap is exactly what Halliday says today’s aggregators must close before attempting an IPO. Both executives suggest that an IPO should not be treated as the default endgame for private-equity-backed rollups. Halliday expects more mega RIAs to pursue recapitalizations, such as MAI Capital Management’s March 2025 deal giving Carlyle a majority stake, rather than public listings. “Being a publicly traded company isn’t always the right thing for the company,” he said. “There’s a lot of reasons to stay private.”
Amar adds that the choice should partly depend on the demands of being a public entity. “For consolidators considering an IPO, the bigger question may not be whether the underlying business is good, since many RIA platforms clearly are,” he said. “It is whether the organization is ready for the scrutiny, disclosure obligations, and quarterly cadence that come with being public.” With private capital still abundant and willing to underwrite growth using adjusted EBITDA at attractive multiples, many consolidators can reasonably ask whether staying private and focusing on building the business is the better path for now.
Halliday also notes that consolidators have little reason to rush toward a public listing given the persistent succession pressure across the wealth management sector, which signals that deal flow and the opportunity to build scale the right way will continue. For more on industry trends, see Survey: 69% of Americans Back Mandatory AI Stock Transfers to Public Fund and Focus Financial Network Expands Eastward with Virginia Office, Hires 23-Year Veteran.