The Consumer Price Index for May rose 4.2% from a year earlier, the highest annual reading since April 2023, according to data released Wednesday by the U.S. Bureau of Labor Statistics. The figure, up from 3.8% in April, matched the consensus forecast from economists surveyed by Dow Jones Newswires and The Wall Street Journal. On a seasonally adjusted basis, CPI increased 0.5% month-over-month, also in line with expectations.
Core CPI, which excludes volatile food and energy prices, rose 0.2% in May, below the 0.3% gain economists had anticipated. On a year-over-year basis, core CPI advanced 2.9%, meeting forecasts. The energy index climbed 3.9% in May, following a 3.8% rise in April and a 10.9% surge in March, reflecting persistent pressure from elevated oil prices.
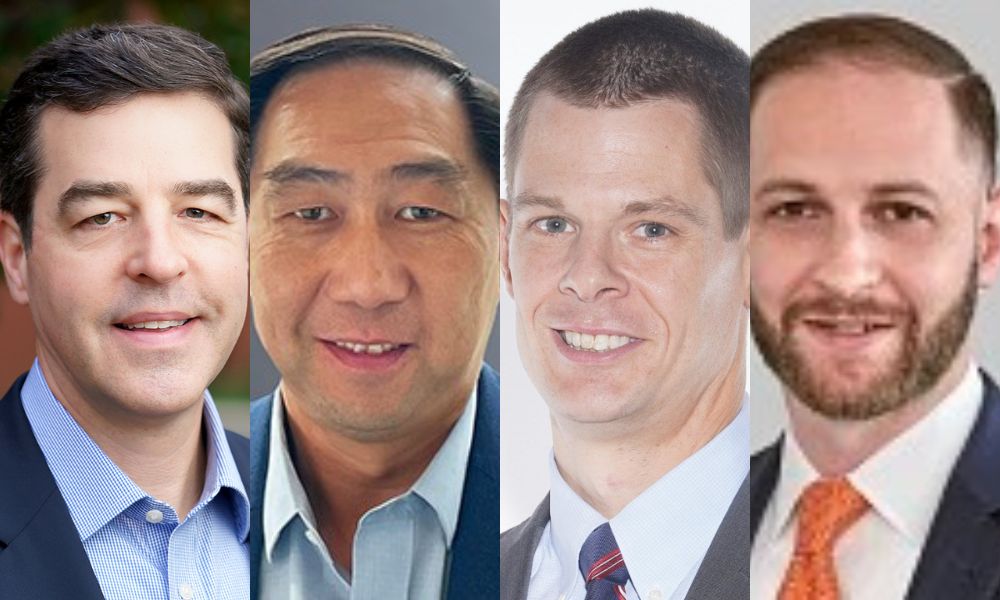
“Most of this morning’s data came in line with expectations,” said Chris Zaccarelli, chief investment officer at Northlight Asset Management. However, Zaccarelli warned that the inflation trajectory could force the Federal Reserve to reverse course. “More importantly – and the market has started to react to this possibility – the Fed’s next move may need to be a hike, and not a cut as many had expected coming into this year,” he said. The S&P 500 ended Wednesday’s session down more than 1.6% as investors digested the implications.
Higher inflation has weighed on consumer sentiment, according to Wei Hu, vice president of financial research and strategy at Edelman Financial Engines. “The Middle East conflict is still unresolved, so Americans have been paying more at the gas pump for months now and energy has been an increasing contributor to the headline CPI,” Hu said. “Higher inflation, combined with recent good news on the employment front, tilts the playing field more toward the Federal Reserve leaving interest rates high or even increasing them.”
David Doyle, head of economics at Macquarie Group, sees the next Federal Open Market Committee move as a likely 25-basis-point rate hike in the first quarter of 2027, with risks tilted toward an earlier date. “While the inflation profile ahead hinges on the trajectory of energy prices, we anticipate underlying pressures to remain in core CPI with both this (and core PCE) likely to remain comfortably above the 2% target for the foreseeable future,” Doyle said in a note.
Not all analysts are convinced a hike is imminent. Josh Jamner, senior investment strategy analyst at ClearBridge Investments, argued that the U.S. economy has managed the recent oil-price shock relatively well. “With core measures suggesting more limited price increases and much of the upside coming from oil directly (energy) or indirectly (airfares), today’s release suggests that inflationary pressures stemming from the oil price shock have remained manageable for the U.S. economy so far,” Jamner said.
The latest CPI data arrives amid a broader backdrop of elevated inflation and revised economic growth. The Q1 GDP was revised down to 1.6%, while April PCE inflation hit 3.8%, further dimming hopes for near-term rate cuts. Meanwhile, the AI infrastructure capital expenditure is projected to reach $800 billion by 2026, a trend that could add to both S&P 500 gains and inflationary pressures.
For financial advisors, the data reinforces the need to prepare clients for a potentially prolonged period of elevated rates. The SOA survey found that 59% of retirees left the workforce earlier than planned, citing inflation and caregiving strains as key factors. Advisors may need to revisit retirement income strategies and portfolio positioning in light of the shifting rate outlook.



