Retirement savers saw a significant rebound in their 401(k) balances during the second quarter of 2026, according to new data from Principal Financial Group. Average account balances rose 9.6% from the prior quarter and 12.6% year-over-year, driven by improved market performance and steady participant contributions.
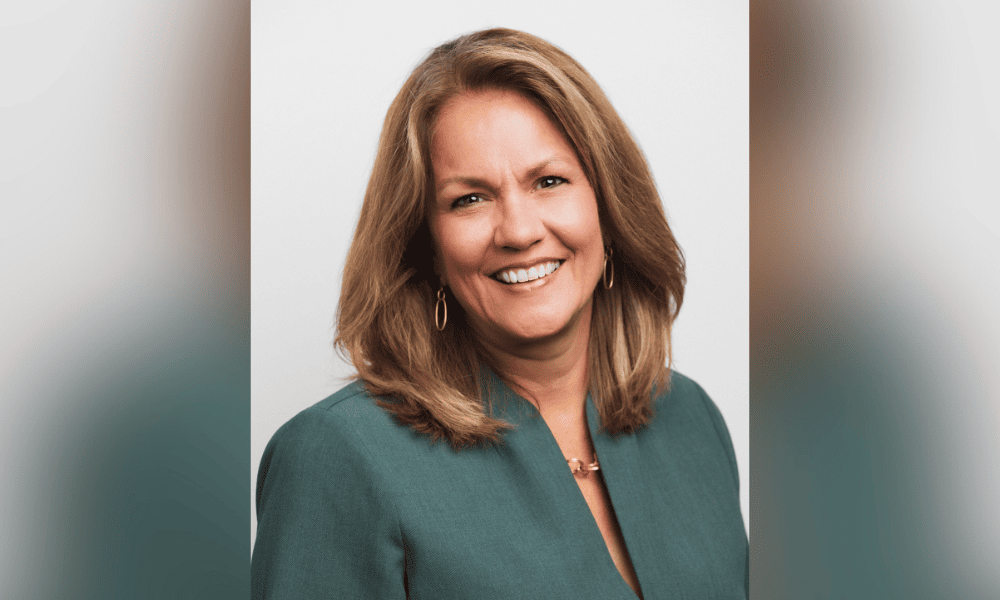
Teresa Hassara, senior vice president of workplace savings and retirement solutions at Principal, attributes the gains to disciplined saving habits rather than reactive market timing. "Improved market performance contributed, but participant engagement remained encouraging," she said. Deferral rates rose 1.8% year-over-year, while plan participation increased 1.5%, indicating that workers largely stayed the course despite economic uncertainty.
Roth 401(k) adoption accelerates across generations
One of the standout trends in the Q2 data is the continued shift toward Roth 401(k) contributions. Overall Roth usage reached 13.1% of participants, up 16.9% from a year earlier. As of June 30, 2026, 89.4% of plans on Principal's platform offer a Roth option, a 20.6% increase since June 2021.
Millennials lead adoption at 15.9%, followed by Gen X at 14.5% and Gen Z at 9.2%. Higher-income earners—those making more than $150,000 annually—are driving much of the growth. Hassara notes that this trend suggests participants are thinking more holistically about tax diversification and future flexibility.
Auto-enrollment and the evolving advisor role
Auto-enrollment adoption rose 5.1% year-over-year, and plans using both auto-enrollment and auto-escalation increased 9.1%. As these features become standard, advisors can shift conversations from simply getting workers enrolled to optimizing savings rates, investment choices, and retirement income strategies. This aligns with broader industry moves, such as new 401(k) advice workflows that aim to integrate retirement planning into broader financial advice.
Younger workers posted the strongest balance growth: Gen Z accounts rose 14.9% quarter-over-quarter, and Millennials saw 13.0% growth. Deferral rates increased across all generations, with Gen X up 3.3%, Gen Z up 3.1%, and Millennials up 2.7%. However, these gains come alongside higher hardship withdrawal rates among younger employees, reflecting the competing financial pressures they face.
Persistent financial strain beneath the surface
Despite the positive headline numbers, 2.6% of participants took a 401(k) loan in Q2, and hardship withdrawal incidence rose 2.2% from Q1 2026. Notably, average hardship withdrawal amounts declined both quarter-over-quarter and year-over-year, suggesting that while more people are tapping their savings, they are withdrawing smaller sums.
Hassara emphasized that advisors must recognize the dual reality: "Younger workers are often balancing retirement saving with other important financial priorities." This is echoed in recent research showing that childless Americans lag in retirement confidence, underscoring the need for personalized guidance.
The data also highlights a broader trend: 69% of employers report workers delaying retirement due to inflation and rising living costs. For advisors, this means helping clients navigate both accumulation and the transition to retirement, especially as automatic features free up time for more strategic planning.
Principal's recordkeeping book, one of the largest in the country, provides a window into the retirement landscape. While the rebound in balances is encouraging, the persistence of loans and hardship withdrawals suggests that many participants remain financially fragile. As Hassara noted, effective advisory support means meeting participants where they are—whether they are just starting to save or nearing retirement.



