The Federal Reserve's June policy meeting revealed a central bank grappling with competing views on the path of interest rates, even as a fresh escalation in Middle East tensions threatens to upend the economic outlook. Minutes from the Federal Open Market Committee's June 16-17 gathering, released Wednesday, showed that while many participants believed the federal funds rate would end the year within or slightly below the current 3.5% to 3.75% target range, a sizable contingent anticipated rates would need to rise above that range.
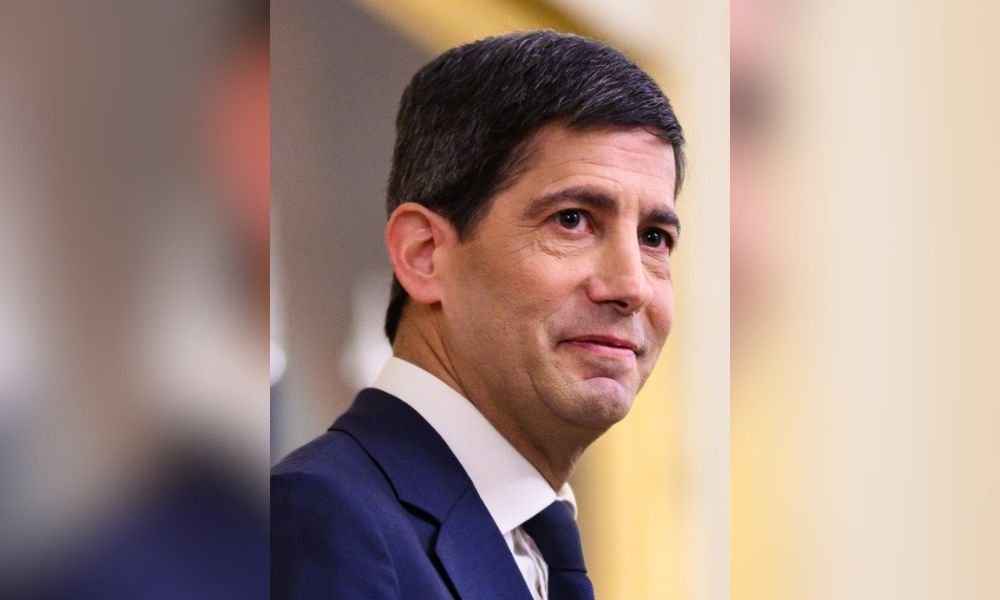
Kevin Warsh, who succeeded Jerome Powell as Fed chair in May, presided over his first rate decision last month, keeping the policy rate unchanged. The minutes describe what Warsh characterized as a “good family fight” over policy direction, underscoring the lack of consensus as the central bank navigates an unusually complex set of crosscurrents.
Jeffrey Roach, chief economist at LPL Financial, said the minutes reflect deliberate ambiguity. “If we can tease out any forward guidance from the minutes, it would be that the committee is working through a wide range of scenarios and will not commit to a specific scenario until the incoming data provides necessary clarity,” Roach wrote in a note Wednesday. He added that he does not expect the committee to alter policy at its next meeting.
The geopolitical backdrop has darkened considerably since the FOMC convened. The U.S. and Iran have traded accusations over attacks on shipping in the Strait of Hormuz, with President Donald Trump declaring a three-week-old ceasefire “over” and describing Iranian leadership as “scum.” U.S. Central Command said Wednesday it had launched additional strikes against Iranian targets to “further degrade their ability to threaten freedom of navigation.”
Oil prices surged in response, with Brent crude and West Texas Intermediate futures both rising more than 6% on Wednesday. The spike revives a risk that had receded in recent weeks: that energy-driven inflation could force the Fed to maintain or even tighten monetary policy.
Inflation itself remains stubbornly above the central bank’s target. The Personal Consumption Expenditures price index, the Fed’s preferred gauge, rose 4.1% year-over-year in May, accelerating from 3.8% in April, according to the Bureau of Economic Analysis. The New York Fed’s June Survey of Consumer Expectations showed median one-year-ahead inflation expectations climbing to 3.7%, the highest in roughly three years, while three-year expectations hit 3.3%, the highest since June 2022.
The FOMC minutes acknowledged the elevated inflation environment, noting that “participants anticipated that inflation would remain elevated in the near term and then begin to decline as the effects of tariffs and energy price increases wane and other supply disruptions related to the closure of the Strait of Hormuz diminish.” Officials judged that risks to the inflation outlook were “still tilted to the upside.”
For financial advisors and their clients, the combination of internal Fed division, geopolitical volatility, and sticky inflation suggests a prolonged period of uncertainty. The minutes predate the latest Middle East escalation, meaning the committee has yet to formally weigh the most recent developments. As Roach noted, the Fed is “working through a wide range of scenarios” and will not commit until data provides clarity. That leaves markets to price in a wide range of outcomes, from rate cuts to further tightening, depending on how events unfold.
Advisors may want to monitor how the situation in the Strait of Hormuz evolves, as a sustained disruption could feed into energy costs and inflation expectations, complicating the Fed’s path. Meanwhile, the Fed is expected to hold rates steady at its next meeting, but the minutes make clear that the debate over the appropriate level of rates is far from settled.



