While the S&P 500 has surged roughly 75% over the past three years, high-net-worth advisors have not abandoned real estate. The State Street Real Estate Select Sector SPDR ETF (XLRE) gained only 15% in the same period, yet wealth managers continue to allocate client capital to property for reasons beyond pure appreciation.
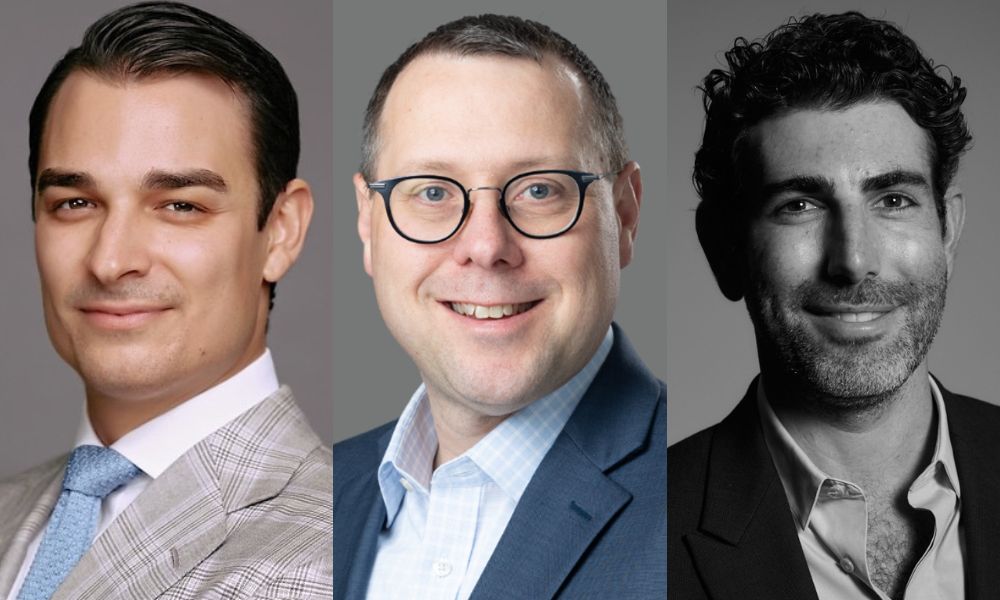
Michael Shawn, founder and CEO of Peregrine Private Client, argues that real estate functions as a multi-purpose tool for affluent families. “The same property can solve a tax problem, a legacy problem, an inflation problem, and a cash-flow problem in the same year,” he said, but only if it is selected, structured, and managed with that breadth in mind. He emphasizes that advisors must first understand a client’s liquidity profile and comfort with long holding periods, then evaluate sponsor quality, lease structures, and tenant alignment.
Matt Dmytryszyn, CIO of Composition Wealth, notes that real estate provides income with low correlation to the broader economy and serves as a long-term inflation hedge. For HNW and UHNW clients, the tax benefits are particularly compelling, including the 20% REIT deduction and depreciation that can offset ordinary income. However, he warns that fees can be substantial: “Underlying managers can get compensated through property acquisition fees, development fees, property management fees, and this can be above and beyond any fund management or performance fees.”
Max DiSesa, managing partner at Seven Bridge Wealth Advisors, points to recent legislative changes that enhance real estate’s appeal. The One Big Beautiful Bill Act made 100% bonus depreciation permanent and codified Opportunity Zones, while 1031 exchanges remain largely intact. “With the new $15 million per person estate exemption, that's a generational outcome you genuinely cannot replicate with a stock portfolio,” DiSesa said. Heirs can receive property at a stepped-up basis, effectively erasing deferred capital gains.
Shawn identifies Dallas-Fort Worth, Raleigh, Charlotte, Savannah, Nashville, Northern New Jersey, Tampa-St. Petersburg, and Manhattan as top emerging markets for 2026. He expects capital flows to remain bifurcated: “Sun Belt and Southeast for growth and select Northeast gateway submarkets for trophy assets and repriced opportunities.” His firm is concentrating on metros with strong housing and daily-needs retail fundamentals, diversified employment bases, and real population tailwinds.
Dmytryszyn cautions that rising interest rates could pressure commercial real estate prices through higher borrowing costs. He notes that 10-year Treasury yields have been range-bound recently, helping markets heal. Meanwhile, excess supply in multifamily and industrial sectors is projected to shift to excess demand over the next one to two years, which could accelerate rent growth and boost industry fundamentals.
DiSesa’s highest conviction real estate call is data centers. National vacancy is below 2%, most facilities are pre-leased before completion, and AI infrastructure spending is driving one of the largest real estate capital cycles in modern history. The main constraint, he says, is the power grid. His second choice is senior housing, driven by demographic trends: “The first baby boomers turn 80 this year, the 80-plus age group is the fastest-growing in the country, and we think new supply has been muted for years.”
For advisors seeking to incorporate real estate into client portfolios, the key is to treat it as a strategic asset rather than a tactical one. As the private real estate trends report notes, opportunities are hiding in plain sight for those who do the due diligence. Meanwhile, the Nitrogen's Legacy Center underscores the importance of engaging heirs early, especially given the $84 trillion wealth transfer underway.



