The recent flurry of professional sports franchise transactions has pushed the asset class into the mainstream of wealth management conversations. On July 11, 2026, the Paul G. Allen estate agreed to sell the Seattle Seahawks to a group led by venture capitalist Vinod Khosla for $9.612 billion, according to ESPN. That price eclipsed the previous NFL record of $6.05 billion set by the Washington Commanders in 2023 and approached the $10 billion paid for the Los Angeles Lakers in June 2025. Just weeks earlier, on June 26, Lukas and Samantha Walton—heirs to the Walmart fortune with a combined net worth of $45 billion per Forbes—acquired a 10% minority stake in the Chicago Bulls and the United Center, valuing the franchise at roughly $6.45 billion, the fifth-highest in the NBA.
Adding to the momentum, on July 23, 2026, Mark Cuban's Harbinger Sports Partners—co-founded with Rashaun Williams, Jonathan Mariner, and Steve Cannon—purchased an undisclosed minority stake in the Athletics ahead of the team's planned move to Las Vegas in 2028. The firm is targeting $750 million in total capital across 10 to 12 sports investments, according to TheStreet. These deals come as the World Economic Forum's Global Sports Report 2025 projects the global sports economy to grow from $2.3 trillion in 2025 to $8.8 trillion by 2050.
For advisors serving ultra-high-net-worth clients, the question is no longer hypothetical: how should they evaluate sports as an investment? Three industry experts offer frameworks for navigating this emerging asset class.
Alpha over beta in sports investing
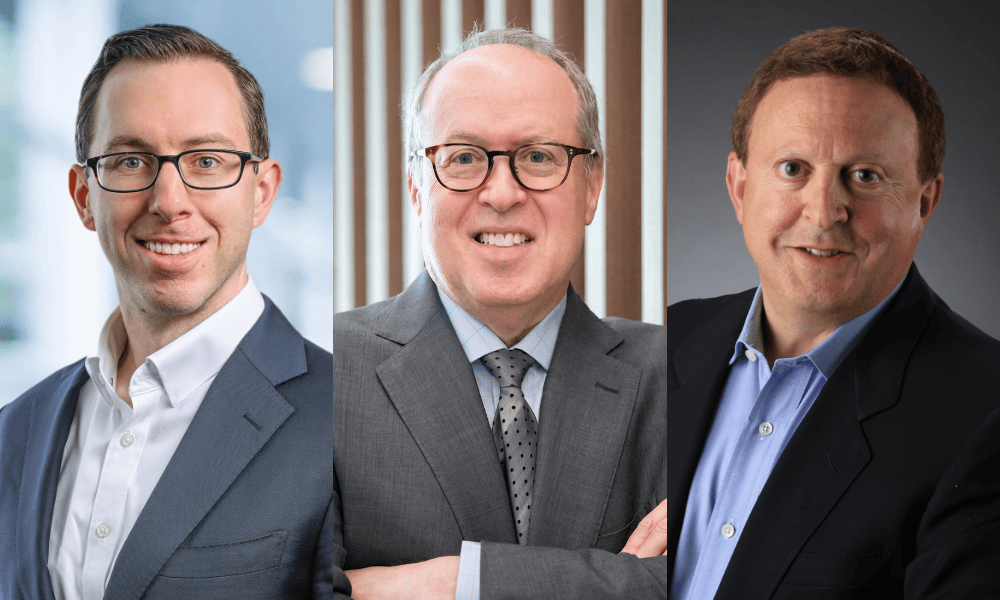
Kurt Nye, managing partner and CIO at MAI Capital Management, draws a sharp distinction between what he calls "sports beta" and "sports alpha." Broad exposure to rising franchise valuations—beta—is not inherently compelling, he argues. Instead, he focuses on opportunities with experienced operators who have credible value-creation plans: consolidating fragmented sports-adjacent industries, professionalizing family-owned businesses, and accessing private equity, private debt, real estate, and venture capital within the sports ecosystem.
"There is a misunderstanding that sports investing is mostly about purchasing stakes in teams," Nye said. "Sports assets often carry unique traits like a highly sticky consumer base, strong barriers to entry, and contractual revenue streams. We're less enthusiastic about sports 'beta' exposure and we're looking at those value creation levers as a way to drive alpha." MAI's five-decade history in sports provides a sourcing network that most advisors cannot replicate, surfacing deals across fund structures and direct investments.
Scarcity and access define the market
Ronald Diamond, founder and chairman of Diamond Wealth Strategies, emphasizes two structural facts: profitability and scarcity. Major franchises generate recurring revenue from media rights, sponsorships, tickets, and arena economics. With only 32 NFL teams and 30 NBA teams, the supply of assets is fixed and rarely traded, while the pool of qualified buyers is deep. Diamond has identified at least 156 billionaire families with publicly known sports investments, and he believes the actual number is higher given the prevalence of private minority stakes.
"Scarcity matters. There are only 32 NFL teams and 30 NBA teams. These assets rarely come up for sale, and there are far more qualified buyers than available franchises," Diamond said. "Having the money does not guarantee access. A family may be able to write the check and still never see the opportunity because many of these deals stay within a small circle." For families without a controlling stake, he recommends direct minority co-investments alongside lead owners or family-office consortiums, which are typically shared through relationships rather than marketed broadly. Funds offer an alternative, but Diamond stresses rigorous review of manager quality, fees, and asset selection. He also points to women's sports and emerging leagues as smaller entry points with upside—and higher operating risk.
Women's sports and emerging leagues offer ground-floor entry
Joel R. Freedman, managing director and founder of Eclipse Private Wealth Management, echoes the scarcity and uncorrelated-return thesis. Television rights remain valuable because live sports are one of the few programming forms that draw massive, loyal audiences. For advisors, the key is to help clients distinguish between the allure of owning a team and the financial realities of the investment. As the sector matures, opportunities are expanding beyond franchise ownership into funds, co-investments, and sports-adjacent businesses.
For advisors, the practical takeaway is to prepare a framework for client conversations. As recent warnings about single-asset vehicles illustrate, due diligence is critical. The blending of public and private assets in new funds also reflects the broader trend. While sports investing may not suit every portfolio, the recent deals have made it a topic that advisors can no longer ignore.



